REFINANCING OPTIONS FOR HOMEOWNERS
Put Your Mortgage to Work for Your Next Goal
Your mortgage needs can change as your life, financial goals, and the market change. Refinancing may provide an opportunity to adjust your loan terms, access available home equity, consolidate certain debts, or restructure your mortgage to better align with your goals.
REFINANCING EXPLAINED
What Does It Mean to Refinance Your Mortgage?
Refinancing replaces your existing mortgage with a new loan. Homeowners may choose to refinance for a variety of reasons, including changing the loan term, accessing available home equity, consolidating certain debts, or restructuring their financing as their needs change.
Whether refinancing makes sense depends on your goals, current mortgage, available equity, qualifications, closing costs, and market conditions. The right strategy isn't simply about finding a different interest rate—it's about determining whether a new loan supports your overall financial objectives.
Common Refinancing Goals
✓ Adjust the mortgage term or loan structure
✓ Access available home equity
✓ Consolidate certain higher-cost debts
✓ Potentially reduce a monthly mortgage payment when circumstances allow
Refinance programs, terms, and eligibility requirements vary by lender and loan program. Qualification may depend on available home equity, property value, existing mortgage balance, credit, income, debt-to-income ratio, loan amount, occupancy, and other underwriting requirements. Refinancing replaces your existing mortgage with a new loan and may involve closing costs and other fees. Refinancing may not be beneficial in every situation, and accessing home equity through a cash-out refinance will increase the amount borrowed and may affect your monthly payment and total interest paid over the life of the loan.
REFINANCING GOALS
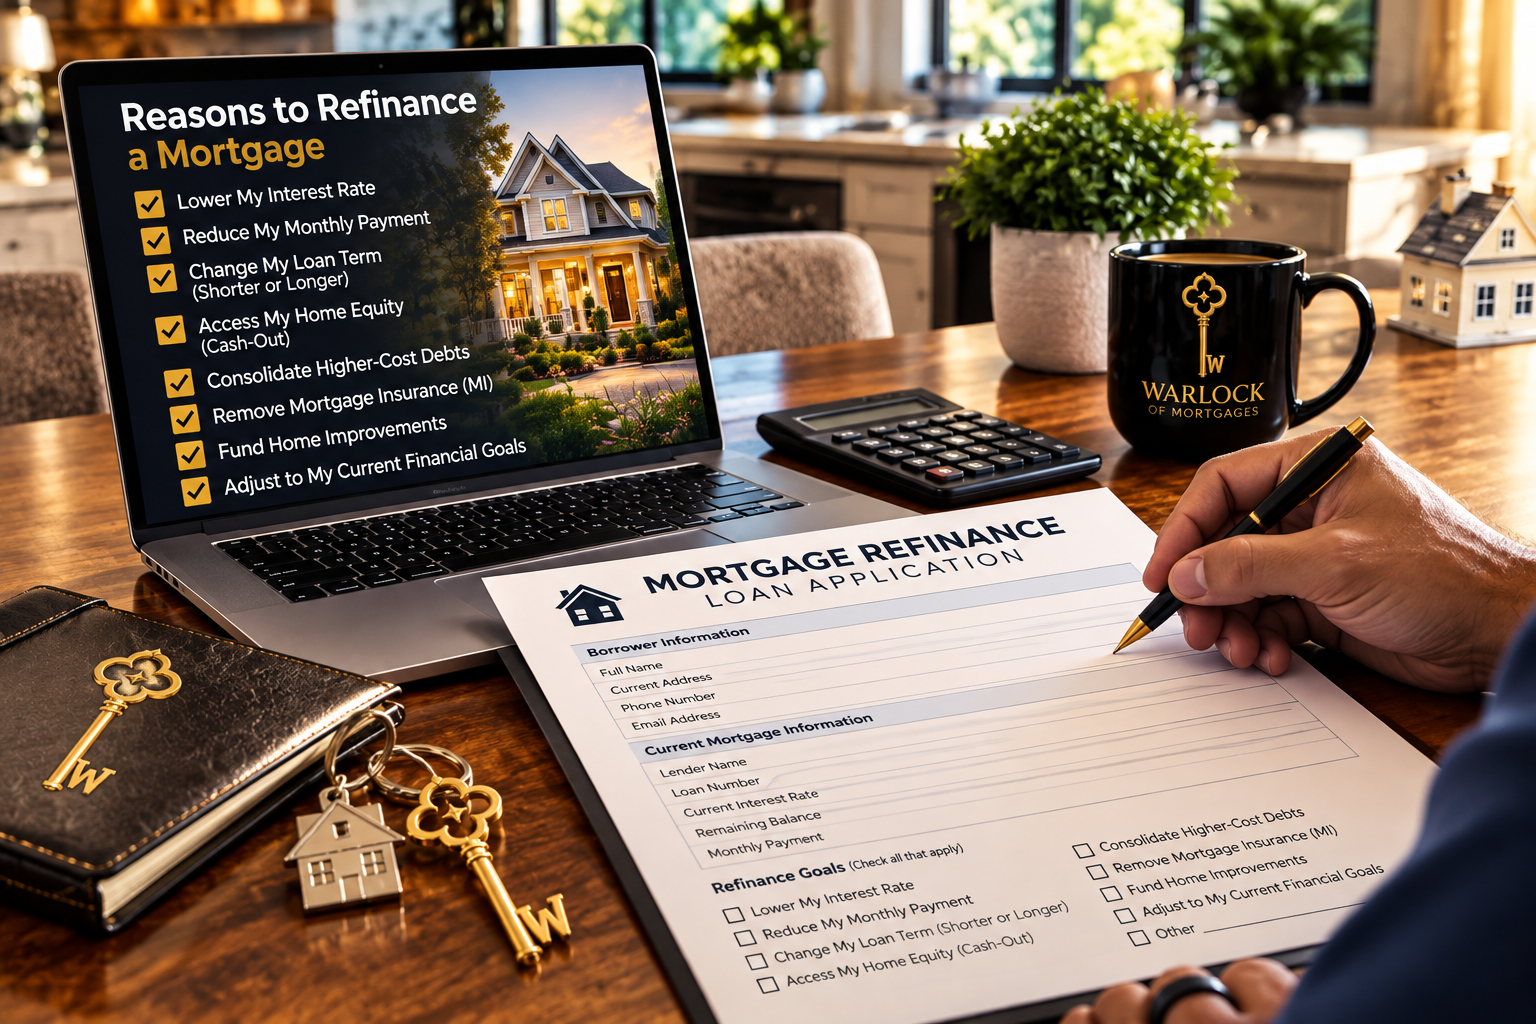
What Could Refinancing Help You Accomplish?
Refinancing can serve different purposes depending on your current mortgage and financial goals. Understanding what you want to accomplish is an important first step in determining which refinance strategy may be worth exploring.
Lower or Restructure Your Payment
Explore whether a new loan structure, term, or available market rate could better align your mortgage payment with your current financial goals.
Change Your Loan Term
Move to a shorter or longer repayment term depending on whether your priority is paying off your mortgage sooner or restructuring your monthly obligation.
Access Home Equity
A cash-out refinance may allow eligible homeowners to convert a portion of their available home equity into funds for other financial needs.
Consolidate Certain Debts
Available equity may provide an opportunity to consolidate certain higher-cost debts into a new mortgage as part of an overall refinance strategy.
Review Mortgage Insurance
Depending on your current loan, equity position, and new loan program, refinancing may provide an opportunity to change or eliminate certain mortgage insurance requirements.
Fund Home Improvements
Available home equity may help fund renovations, repairs, or improvements without requiring a separate home-improvement loan.
REFINANCE LOAN OPTIONS
Explore Different Ways to Refinance
The right refinance option depends on your existing mortgage, available equity, qualifications, and what you want your new loan to accomplish. Here are several refinance strategies that may be available depending on your situation.
Rate-And-Term Refinance
Replace your current mortgage with a new loan while adjusting the interest rate, repayment term, or both, without taking significant additional cash from the property's equity.
Cash-Our Refinance
Replace your existing mortgage with a larger loan and receive a portion of the available equity in cash, subject to program limits and qualification requirements.
Conventional Refinance
Conventional refinancing may offer options for changing your loan term, restructuring your mortgage, accessing available equity, or addressing mortgage insurance depending on eligibility.
FHA Refinance
Homeowners with eligible FHA financing may have refinance options designed for different goals, including certain streamlined refinance programs or cash-out transactions when requirements are met.
Veteran Refinance
Eligible borrowers with VA-backed financing may have access to refinance options such as an Interest Rate Reduction Refinance Loan (IRRRL), while other VA refinance options may allow qualified borrowers to access equity.
USDA Refinance
Eligible homeowners with USDA financing may have refinance options that can restructure an existing USDA mortgage, subject to USDA program requirements and eligibility.
THE REFINANCING ROADMAP
Your Path from Review to Closing
Refinancing doesn't have to be complicated. We'll review your current mortgage, discuss what you want to accomplish, explore available refinance options, and help you understand the process from application through closing.
STEP 1
Review Your Current Mortgage
We start by looking at your existing loan, current balance, payment, interest rate, loan term, and available home equity.
STEP 2
Define Your Goals
We'll discuss what you want the refinance to accomplish, whether that's changing your loan structure, accessing equity, consolidating certain debts, or another financial objective.
STEP 3
Explore Your Options
We'll compare refinance programs and potential loan structures based on your goals, qualifications, property, and available options.
STEP 4
Application & Underwriting
You'll provide the documentation needed for the new loan while the property, income, assets, credit, and other applicable requirements are reviewed.
STEP 5
Closing Your New Loan
Once the refinance is approved and applicable closing requirements are satisfied, you'll complete the final documents and your new mortgage will replace the existing loan.
WHAT YOU'LL NEED
Preparing for Your Refinance
The documentation needed for a refinance can vary depending on the loan program, property, employment, income, and your individual financial situation. Having the following information available can help make the process more efficient.
Income & Employment
Recent pay stubs, W-2s, tax returns, or other income documentation may be requested depending on your employment and the refinance program.
Assets & Finances
Bank statements and other financial documentation may be needed to verify assets, reserves, or funds required for closing.
Current Mortgage & Property
Information about your existing mortgage, homeowners insurance, property taxes, HOA if applicable, and the property itself may be needed during the refinance process.
Identification & Credit
Valid identification and authorization to review your credit and financial obligations are typically part of the refinance application process.
READY TO EXPLORE YOUR OPTIONS?
See If Refinancing Fits Your Goals
Whether you're looking to restructure your mortgage, access available equity, or simply understand what refinance options may be available, I'm here to help you evaluate the possibilities and determine your next step.