FLEXIBLE ACCESS TO YOUR HOME EQUITY
HELOC Financing That Puts Your Home Equity Within Reach
A Home Equity Line of Credit (HELOC) may allow qualified homeowners to access available home equity through a revolving line of credit while keeping their existing first mortgage in place. Whether you’re planning home improvements, managing major expenses, or simply want flexible access to funds when you need them, we’ll help you understand how a HELOC works and whether it fits your financial goals.
Start Your ApplicationHELOC FINANCING EXPLAINED
Flexible Access to Your Home Equity When You Need It
A Home Equity Line of Credit (HELOC) is a revolving line of credit secured by the equity in your home. Unlike a traditional home equity loan that generally provides funds in one lump sum, a HELOC may allow qualified homeowners to borrow funds as needed during an established draw period, up to their approved credit limit.
As funds are repaid, the available credit may be replenished during the draw period, subject to the terms of the loan. HELOCs commonly have variable interest rates, which means the interest rate and payment may change over time. Your available credit, terms, and qualification depend on factors such as home equity, property value, credit, income, existing mortgage balances, and lender requirements.
HELOC Highlights
✓ Revolving access to available home equity during the draw period
✓ Borrow funds as needed up to your approved credit limit
✓ Available credit may replenish as borrowed amounts are repaid during the draw period
✓ Keep your existing first mortgage in place
✓ Funds may be used for home improvements, major expenses, debt consolidation, or other financial goals
HELOC programs, terms, and eligibility requirements vary by lender. HELOCs commonly have variable interest rates, which means the interest rate and payment may change over time. Qualification may depend on available home equity, property value, existing mortgage balances, credit, income, debt-to-income ratio, loan amount, and other underwriting requirements. A HELOC is secured by your home and creates an additional lien on the property.
WHY CONSIDER A HELOC?
Flexible Access to Your Equity for Life’s Bigger Expenses
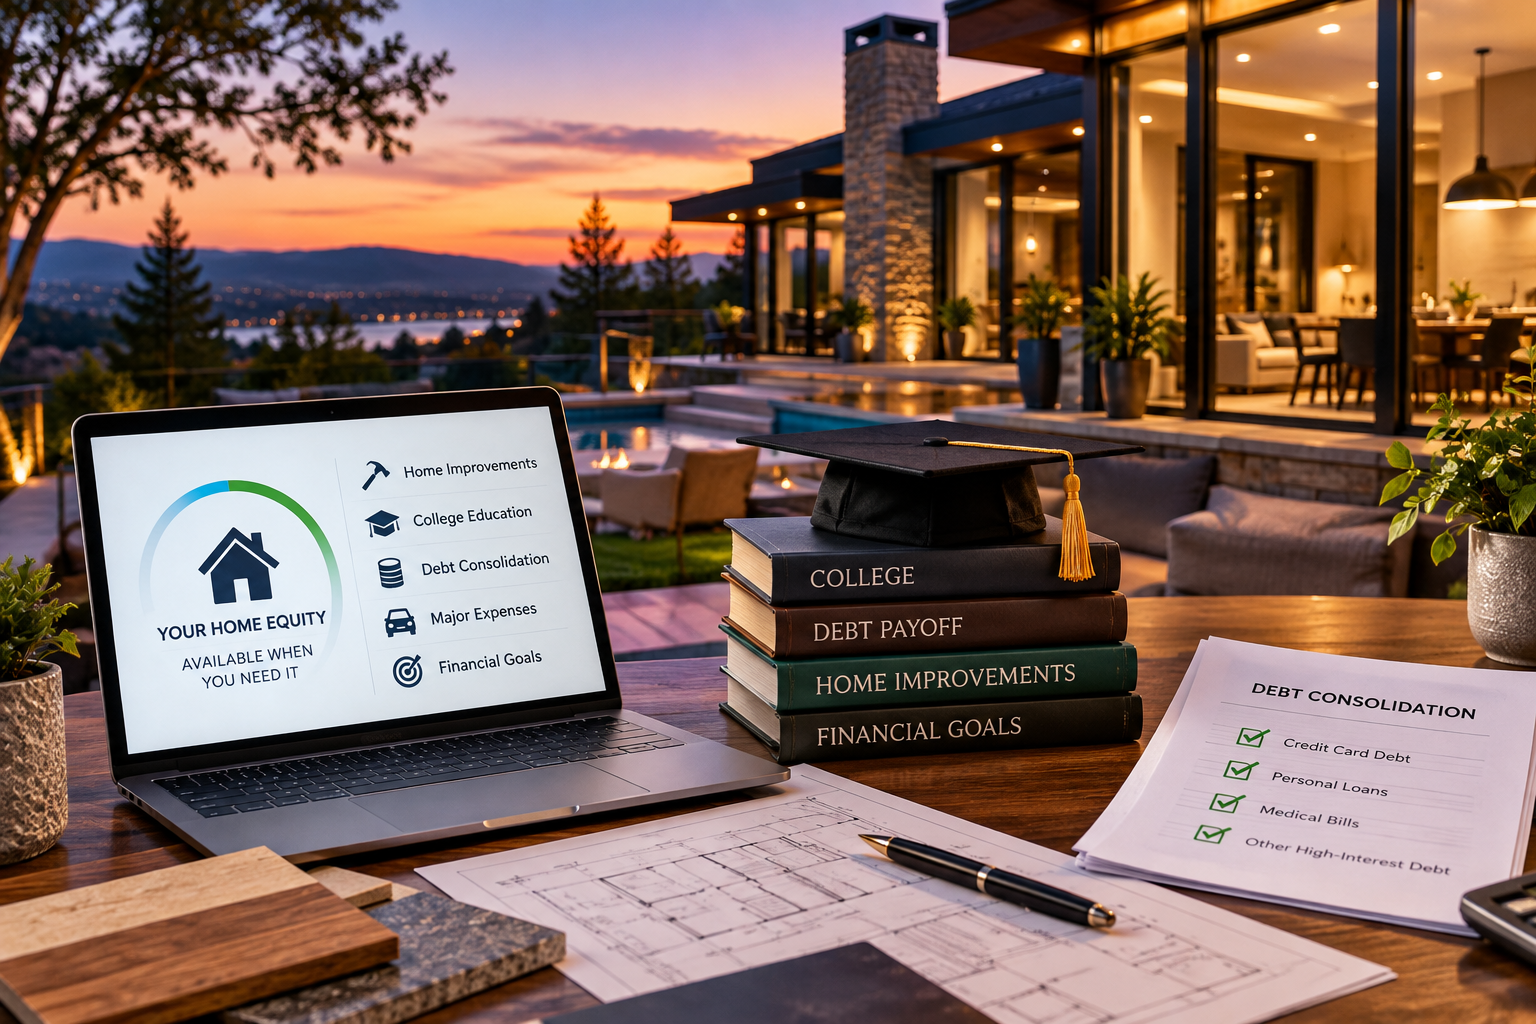
A HELOC can give qualified homeowners flexible access to available home equity without requiring them to borrow the full amount upfront. Because you can draw funds as needed during the draw period, it can be useful for projects or expenses that happen over time—such as home improvements, college costs, debt consolidation, or other major financial needs.
Borrow Only What You Need
Unlike a lump-sum loan, a HELOC allows you to draw from your approved credit line as needed during the draw period, so you can access funds when expenses arise rather than borrowing the entire amount upfront.
Flexible Access Over Time
During the draw period, you may be able to access your available credit multiple times as needs arise. As borrowed amounts are repaid, that credit may become available to use again, subject to the terms of your HELOC.
Keep Your First Mortgage in Place
A HELOC is generally secured as an additional lien on your home, allowing you to access available equity without replacing your existing first mortgage. This may be useful if you want to preserve the terms of your current first mortgage.
Use Your Equity for a Variety of Goals
HELOC funds may be used for home improvements, education costs, debt consolidation, major purchases, or other financial needs, giving you flexibility to use your available equity based on your priorities.
HELOC FINANCING OPTIONS
HELOC Options for Different Home Equity Goals
HELOCs can be structured differently depending on the lender, your qualifications, and how you plan to use your home equity. Understanding the available structures can help you choose an approach that provides the flexibility, access to funds, and repayment features that align with your financial goals.
Variable-Rate HELOC
Many HELOCs have a variable interest rate that can change over time based on the loan’s terms and applicable index. This structure provides revolving access to available home equity during the draw period, while payments and borrowing costs may change as interest rates change.
Fixed-Rate Conversion HELOC
Some HELOC programs may allow you to convert all or a portion of an outstanding variable-rate balance to a fixed interest rate for a specified term. This feature can provide more predictable payments on the converted balance while maintaining access to the remaining available credit, subject to the loan’s terms.
Interest-Only Draw Period HELOC
Some HELOCs may allow interest-only payments on the amount borrowed during the draw period. When the repayment period begins, payments generally increase because principal repayment is added. Terms and payment structures vary by lender and program.
HELOC for Ongoing Expenses
A HELOC’s revolving structure can be useful when expenses occur over time rather than all at once. Qualified homeowners may draw funds as needed for projects such as renovations, college expenses, or other planned costs, up to the available credit limit during the draw period.
A FASTER WAY TO ACCESS YOUR HOME EQUITY
Discover Your Home’s Financial Flexibility with the AXEN HELOC
The AXEN HELOC offers qualified homeowners a streamlined way to access available home equity through a fast, technology-driven process. With automated approval that may be completed in minutes and eligible loans potentially closing in as little as five days, it can provide convenient access to funds for home renovations, debt consolidation, education expenses, or other major financial needs.
Fast Automated Approval
AXEN’s technology-driven process may provide eligible borrowers with an automated approval decision in as little as five minutes, helping simplify and accelerate the HELOC process.
Close in as Little as 5 Days
Eligible AXEN HELOC's may close in as little as five days, providing qualified homeowners with a faster path to accessing available home equity when timing matters.
Credit Lines Up to $400,000
Qualified homeowners may be eligible for an AXEN HELOC with a credit line of up to $400,000, depending on available home equity, borrower qualifications, property eligibility, and program requirements.
Flexible Ways to Use Your Equity
Use available HELOC funds for home renovations, debt consolidation, college expenses, major purchases, or other financial needs—giving you flexibility to put your home equity toward the goals that matter to you.
AXEN HELOC availability, credit limits, approval times, closing times, rates, terms, and eligibility are subject to borrower qualifications, property eligibility, program requirements, and lender guidelines. Not all borrowers will qualify for the maximum credit line or accelerated approval and closing timelines.
Explore the AXEN HELOCYOUR HELOC ROADMAP
From Available Home Equity to a Flexible Line of Credit
Opening a HELOC involves evaluating your available home equity, reviewing your financial qualifications, and determining the credit line that may be available to you. We’ll help you navigate the application, property valuation, underwriting, and closing process so you understand how your HELOC works before you begin accessing funds.
STEP 1
Review Your Goals & Home Equity
We’ll discuss how you plan to use the HELOC, review your existing mortgage, and evaluate your available home equity to help determine whether a HELOC may fit your financial goals.
STEP 2
Explore Your HELOC Options
We’ll review available HELOC programs, estimated credit limits, rate structures, draw periods, repayment terms, and qualification requirements to help identify an option that aligns with your needs.
STEP 3
Complete Your HELOC Application
We’ll complete your HELOC application and gather the required income, asset, credit, property, and existing mortgage documentation for the lender’s review.
STEP 4
Property Valuation & Loan Review
The lender evaluates your property value, available equity, existing mortgage balance, and other loan details. An appraisal or another acceptable property valuation method may be required, depending on the HELOC program.
STEP 5
Underwriting & Final Approval
The lender reviews your complete loan file, including credit, income, debts, property value, available equity, and other applicable requirements before issuing final HELOC approval.
STEP 6
Close & Access Your Credit Line
Once your HELOC is approved and all closing requirements are satisfied, you’ll sign the final documents. After any applicable waiting period and funding requirements are met, your credit line becomes available according to the terms of your HELOC.
WHAT YOU’LL NEED
Preparing for Your HELOC
HELOC qualification typically considers your income, credit, existing debts, property value, available home equity, and current mortgage obligations. Having your financial and property documentation organized can help keep the process moving smoothly from application through closing.
Income & Employment
Recent pay stubs, W-2s, tax returns, or other applicable income documentation may be needed to verify your income and employment, depending on the HELOC program and how you earn your income.
Current Mortgage Information
Be prepared to provide information about your existing first mortgage, including the current loan balance, monthly payment, and details about any other liens secured by the property.
Property Information
Property details, homeowners insurance information, property tax records, and an appraisal or other acceptable valuation may be needed to help determine the home’s value and available equity.
Credit & Debt Information
Your credit history and existing monthly debt obligations may be reviewed to help determine eligibility, debt-to-income ratio, available credit line, and HELOC terms.
Assets & Reserves
Bank statements, investment account statements, or other asset documentation may be requested to verify available funds and reserves, depending on the HELOC program and qualification requirements.
Identification & Additional Documents
Government-issued identification and other personal documentation will be needed, along with any additional information requested by the lender to complete the HELOC review and approval process.
READY TO PUT YOUR HOME EQUITY TO WORK?
Let’s Put Your Home Equity to Work for Your Goals
Whether you’re planning home improvements, paying for college, consolidating higher-interest debt, or simply want flexible access to your available home equity, I’ll help you understand your HELOC options and determine whether a home equity line of credit aligns with your financial goals.